
Bruce Lawner
Chief Operating Officer of Bayport Funding
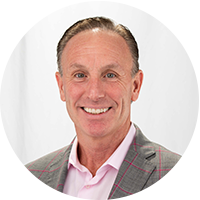
Bruce Lawner is the Chief Operating Officer of Bayport Funding, a direct bridge lender for real estate developers and investors, where he directs in-house underwriting, draw management, and loan operations.
He has spent more than 30 years in mortgage banking, including over 15 years as Executive Vice President at Franklin First Financial, Ltd., where he ran both the retail and wholesale lending platforms.
He holds an FHA Direct Endorsement (DE) underwriting designation, an NMLS license, and a New York State Real Estate License, each maintained continuously throughout his career.
Bayport Funding has originated more than $2.2 billion, and Lawner authors the firm’s guidance on draw management and operational execution.
30+ years in mortgage banking | 15+ years as EVP at Franklin First Financial | Founding Executive, First Rehab Lending (2014)
Operational Leadership at Bayport Funding
At Bayport Funding, execution determines whether the firm earns a borrower’s commitment, and Lawner is accountable for that execution. He directs underwriting workflows, draw management, vendor relationships, and compliance, moving each loan from approval through funding to payoff.
Borrowers and brokers choose a capital partner on execution. The responsiveness they depend on is the standard Lawner sets and enforces.
“That originator background never left me. It’s the reason I still think about operations from the borrower’s perspective first.”
From Loan Originator to Chief Operating Officer
Lawner has worked at every level of the business. He began as a loan originator, working leads and learning what makes a deal work for a borrower, and he built on that foundation as he advanced.
At Franklin First Financial, Ltd., he spent more than 15 years rising to Executive Vice President while running the retail and wholesale platforms at the same time. Managing two channels with fundamentally different dynamics required a systems-level command of the full operation, a discipline he carried into Bayport Funding.
Founding First Rehab Lending
In 2014, Lawner acted on an opportunity the conventional market was overlooking. As the mortgage market tightened after the financial crisis, fix-and-flip investors and rehab operators were left without lenders who understood their business model.
He co-founded First Rehab Lending LLC as a founding executive and built the platform from nothing. He wrote underwriting standards for borrower profiles that conventional credit boxes were never designed to serve, established the operating playbook as the business scaled, built the team and its culture, and secured the capital partnerships that funded it.
The platform succeeded, and Lawner has worked in private institutional lending since. It is where he sharpened the credit discipline he now applies at Bayport Funding.
“The lenders who survive and grow are the ones who have strong credit discipline on the way up, so they have room to maneuver on the way down.”
Credentials and Licenses
Lawner holds three credentials, each maintained continuously throughout his career: an NMLS license, an FHA Direct Endorsement (DE) CHUMS number, and a New York State Real Estate License.
The FHA Direct Endorsement designation authorizes an underwriter to approve FHA-insured loans without HUD reviewing each file. A lender registers an underwriter for the program only after vouching for their qualifications, which makes it a direct measure of underwriting judgment. That is the standard Lawner applies to Bayport Funding’s in-house underwriting.
His NMLS license registers him in the national system that governs mortgage professionals under federal law. His New York State Real Estate License reflects a working command of the properties Bayport finances and the loans secured by them.
Areas of Expertise
Lawner holds three credentials, each maintained continuously throughout his career: an NMLS license, an FHA Direct Endorsement (DE) CHUMS number, and a New York State Real Estate License.
The FHA Direct Endorsement designation authorizes an underwriter to approve FHA-insured loans without HUD reviewing each file. A lender registers an underwriter for the program only after vouching for their qualifications, which makes it a direct measure of underwriting judgment. That is the standard Lawner applies to Bayport Funding’s in-house underwriting.
His NMLS license registers him in the national system that governs mortgage professionals under federal law. His New York State Real Estate License reflects a working command of the properties Bayport finances and the loans secured by them.
Bruce Lawner is the Chief Operating Officer of Bayport Funding, a direct bridge lender with more than $2.2 billion in originations serving real estate developers and investors across 36 states. With over 30 years in mortgage banking, including founding roles at multiple lending platforms, he writes on operational execution, draw management, and what separates lenders who deliver from those who don’t.


